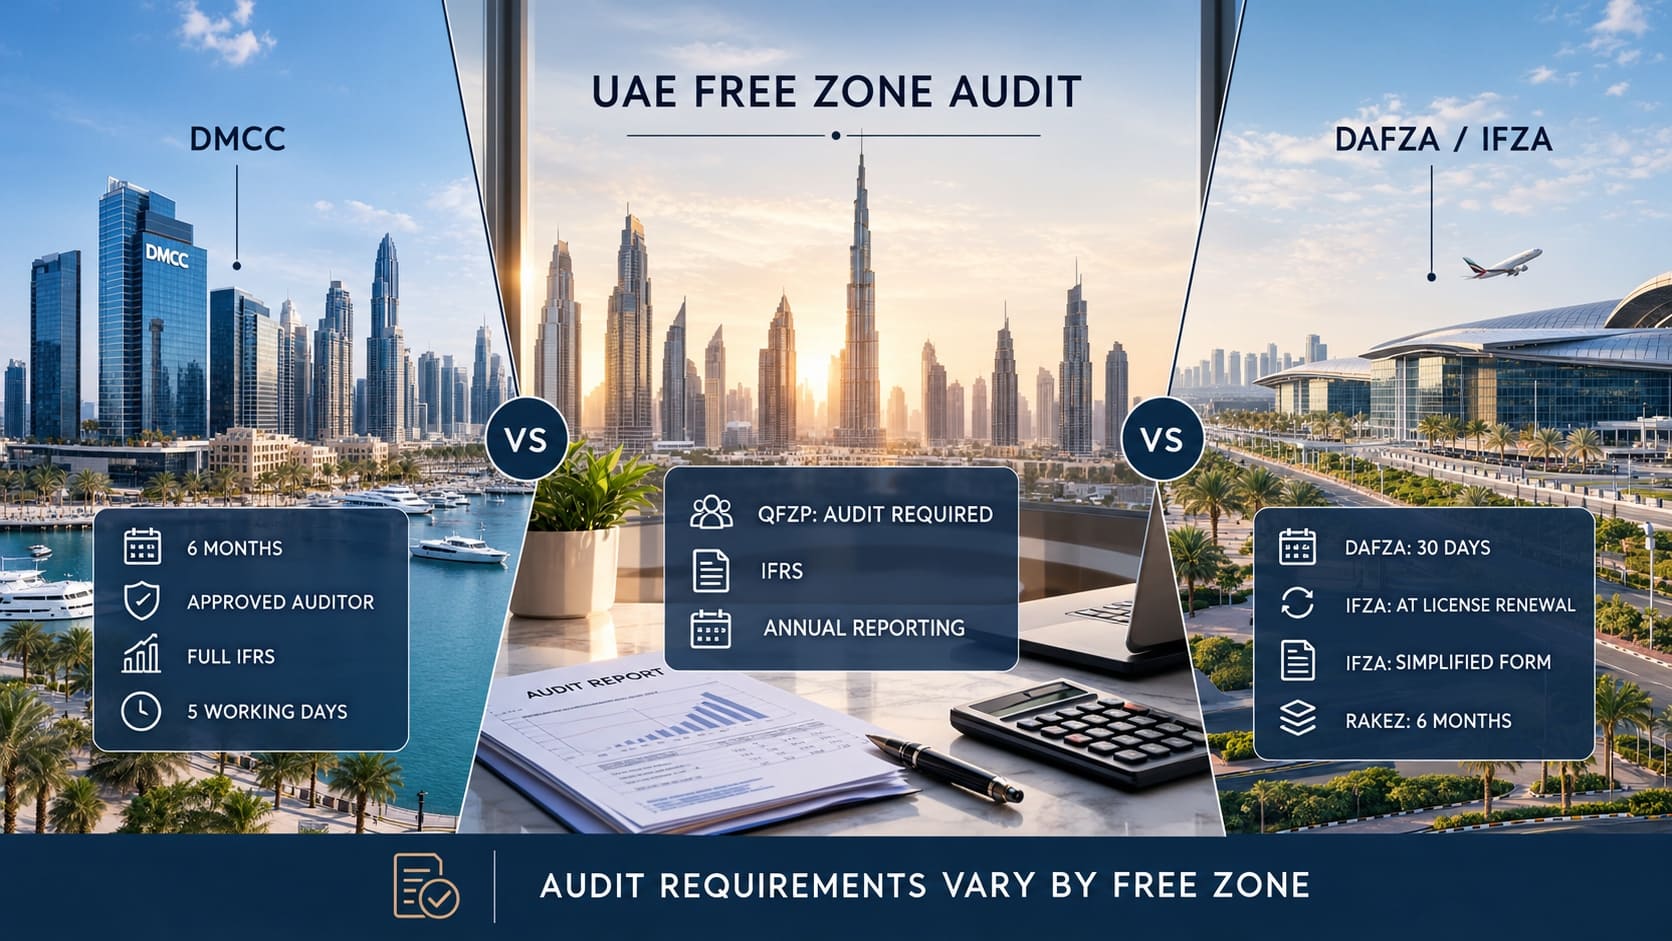
Most people choose a free zone on three things: package price, visa count, how fast the licence is issued. A free zone audit UAE almost never makes that shortlist, and that is a mistake. It is not a one-off formality but an annual obligation that costs money, takes up an accountant’s time and, in some zones, is tied directly to licence renewal. The gap between zones on this point is wider than the gap between their starter packages: one zone gives you six months after year end to file, another sets a thirty-day rule, and a third only asks for audited financial statements on request.
Below is how the requirement actually works across DMCC, DAFZA, IFZA, RAKEZ and other free zones, what federal tax law adds on top, and which questions are worth asking before you file the registration application.
Two layers of requirements that are easy to confuse
The obligation to have an audit comes from two separate directions, and each runs on its own rules.
The first layer is federal and tax-driven. It is uniform nationwide and sets out who must have and retain audited financial statements for Corporate Tax purposes. The second layer is the individual free zone’s own regulations: who must file a report with the authority, by what date, which auditor is allowed to sign it, and what the penalty is for missing that date.
A company can sit outside the federal requirement and still be obliged to file an audit with its free zone — that is exactly how DMCC works. The reverse also happens: a zone may ask for nothing on an annual basis, while the company’s own tax status still forces it to keep audited financial statements on file. Mixing these two layers up is the single most common mistake new companies make.
What UAE tax law requires
The rules changed recently, and plenty of pages online still quote the old reference. The document in force is Ministerial Decision No. 84 of 2025 on Audited Financial Statements, issued 25 March 2025. It repealed the earlier Decision No. 82 of 2023, though that decision still applies to tax periods that commenced before 1 January 2025.
Table 1 — Who must prepare and keep audited financial statements under the tax law
| Category | Basis | Revenue threshold |
|---|---|---|
| Taxable Person (not a Tax Group) | Art. 2(1)(a) | Revenue exceeding AED 50,000,000 for the period |
| Qualifying Free Zone Person (QFZP) | Art. 2(1)(b) | No threshold — audit required at any revenue level |
| Tax Group | Art. 2(2) | Audited special purpose financial statements in the form specified by the FTA |
| Non-Resident | Art. 2(4) | Only revenue through a Permanent Establishment and/or nexus counts toward the threshold |
The second row is the one that matters most. If a free zone company is claiming the zero rate as a Qualifying Free Zone Person, the audit is mandatory regardless of whether it earned one dirham or fifty million. That is not a question of business size; it is a condition attached to the status itself.
The third row is new compared with the previous decision: a Tax Group does not prepare an ordinary consolidated set of accounts but audited special purpose financial statements in the form the FTA specifies. There is also a separate point worth flagging: a Qualifying Free Zone Person distributing goods in or from a Designated Zone has to follow additional FTA procedures on top of the audit requirement itself.
Which reporting standards apply to you
This is governed by Ministerial Decision No. 114 of 2023, dated 9 May 2023. By default, a Taxable Person applies full IFRS. Where Revenue does not exceed AED 50 million, IFRS for SMEs is permitted. And where Revenue does not exceed AED 3 million, the accounts can be kept on a cash basis — or, in exceptional circumstances, by application to the FTA.
This is where it gets interesting. Tax law grants a small company that relief, but a free zone’s own regulations can take it away again. DMCC’s regulations require accounts prepared under full IFRS, with no turnover-based tiering and no reference to IFRS for SMEs at all. So a company turning over one and a half million dirhams, which under tax law could legitimately run on a cash basis, still has to file full IFRS accounts with an audit in DMCC. That has a direct effect on running costs and on the kind of accountant you need to hire.
DMCC: six months, its own auditor list and five business days
DMCC is the most tightly regulated of the high-volume zones, and its rules are worth going through in detail because most other zones’ frameworks are measured against them. The regulations in force are the DMCCA Company Regulations, issued 10 October 2024 and updated 2 January 2025.
The regulations allow six months after financial year end for the accounts to be prepared, approved by the directors, examined by an auditor approved by DMCCA, and laid before a General Meeting of members together with the auditor’s report. Then comes the deadline almost nobody remembers: a copy of the accounts and the report must be filed with the Registrar within five business days of that General Meeting — not after the audit is finished, not at any point during month six, but specifically after the meeting itself.
The auditor cannot be chosen freely. A company may only appoint a firm registered with DMCCA as an approved auditor, and the report must be signed by a partner holding a Ministry of Economy certificate. The rules governing those auditors have themselves been updated: the version currently in force is the Approved Auditor Rules, version 3.0, June 2025, which fully replaced the 2019 edition.
Some requirements here have no equivalent elsewhere. The auditor’s report must confirm the company only carries on activities permitted under its licence, with any income earned outside that licence disclosed separately as other income. The auditor must obtain bank balance confirmations and flag specifically where none was available. Alongside the financial statements, a Summary Sheet is filed — a consolidated form the company completes, then the audit firm’s partner signs and stamps.
There is one exemption. A company that was dormant for the entire financial year does not prepare individual accounts and does not go through an audit. But members holding at least 10% of the nominal value of the share capital can demand both; the notice must be filed no earlier than the start of the relevant year and no later than a month after it ends.
There is no dedicated late-filing penalty line in DMCC’s fine schedule. Instead it falls under the catch-all item for non-compliance with any other DMCC rule, regulation, policy or requirement, carrying a AED 5,000 fine per breach — with DMCCA also entitled to escalate to suspension or cancellation of the licence. Records must be kept for five years.
DAFZA: thirty days in the regulations and a question to put in writing
DAFZA DAFZA operates under the Implementing Regulations 2021, approved by Administrative Resolution ADM 004 of 2021 and issued 14 March 2021. The Registrar keeps its own list of approved auditors, published on the zone’s website.
Now for the deadlines — and this is where care is needed. DAFZA’s regulations contain two provisions that do not sit comfortably together. Regulation 65.3(b) gives an FZCO six months after financial year end to appoint an auditor. Regulation 67.5, meanwhile, requires that within thirty days of financial year end the FZCO’s accounts be prepared, approved by directors and audited. A further thirty days is then allowed to file with the Registrar once the auditor has issued its report.
Those two provisions do not reconcile cleanly, and that is not a nitpick — it is a genuine reason to confirm the actual timeline with the Registrar in writing rather than relying on a blog post. For non-compliance with the reporting requirements, the regulations set out a fine, with the amount left to the administration to determine.
Two further details worth noting. DAFZA requires records to be kept for at least six years, against five in DMCC (and fifteen years for records connected to real estate), and the zone builds in auditor rotation: an auditor cannot consent to appointment if it, or a party related to it, has already audited the company within the prescribed period.
Tell us your expected turnover, headcount and whether you need QFZP status, and we will tell you which zone keeps your annual reporting cheaper and where you will not have to change accountants a year in.
IFZA: reporting tied to licence renewal
IFZA IFZA was long seen as the zone with the lightest reporting load, and its reputation with small business rested on that. That has now changed.
According to the zone’s own published information, from 30 September 2025 every IFZA licensee — both FZCO entities and Branches — files financial statements as part of the trade licence renewal, every year. Anyone who renewed before that date skipped that cycle, but the next renewal will require it. The statements cover the last completed financial year as at the renewal date, with the financial year itself fixed in the company’s memorandum.
IFZA’s logic is fundamentally different from DMCC’s: not everyone needs a full audit. The zone applies two tests at once. If turnover for the completed year does not exceed AED 3 million and the company had no more than nine employees at any point during the year, a simplified statement is enough — but strictly on IFZA’s own template; no other format is accepted. If either test fails, full audited financial statements are required. An employee here is anyone working under a signed employment contract and under the company’s direction, regardless of who sponsors their visa.
Two more practical points. IFZA does not restrict the choice of auditor to its own list — any registered UAE auditor will do. And if an audited report for the same period has already been prepared for the Federal Tax Authority, it can be reused for the renewal instead of commissioning a second one.
RAKEZ and other zones
RAKEZ sits somewhere in the middle. Every company must prepare and file audited financial statements, the deadline is six months from financial year end, and the auditor must come from RAKEZ’s published list of approved firms. The zone is explicit that filing is not required at licence renewal — it is a separate process. Missing the deadline carries a AED 2,500 fine and suspension of services.
Table 2 — How the requirements work in four free zones
| Parameter | DMCC | DAFZA | IFZA |
|---|---|---|---|
| Who must comply | Everyone except dormant companies | Every zone company | Not everyone: a simplified form is available |
| Deadline | 6 months + 5 business days | 30 days under the regulations | By the licence renewal date |
| Auditor | Only from the DMCCA list | Only from the Registrar’s list | Any UAE registered auditor |
| Standards | Full IFRS | As set by the Registrar | By turnover, as under tax law |
| Link to the licence | Separate procedure | Separate procedure | Direct: no report, no renewal |
The remaining major free zones fall between these three models, and the differences between them are substantial.
Table 3 — Other free zones: what the regulations say
| Free zone | Requirement | Particularity |
|---|---|---|
| JAFZA | Audit by a Jafza-approved auditor as a licence condition | General fine up to AED 10,000 per day |
| Meydan | Audited statements submitted only on request | 30 days to respond, not an annual default |
| SHAMS | Accounts prepared and examined by an auditor every year | No filing deadline set in the regulations |
| Ajman Free Zone, SPC Free Zone | Audit regulations not published openly | Confirm by written request to the zone |
Meydan’s model deserves a word of its own. The 2022 regulations require financial statements to be prepared, but the audited version is submitted to the Authority only on request, within thirty days. That does not mean an audit never happens — it means you will not know in advance which year it is needed, and you need to be able to produce it quickly.
On Ajman Free Zone and SPC Free Zone, the honest answer is that their corporate regulations are not published openly, and most of what audit firms write about them online is marketing, not a primary source. The requirement in these zones is confirmed with a written request to the administration before registering.
What to find out before you apply
The answers to five questions affect the cost of owning the company more than any difference in licence price.
Is an audit required at zero revenue — in DMCC that depends on dormant status, while RAKEZ requires it from everyone. Can you use your own auditor, or does the zone run its own approved list, narrowing the pool of firms and setting their terms. Is filing tied to licence renewal — if so, a missed deadline blocks the company rather than just triggering a fine.
Separately, confirm the standard: full IFRS for a small company means a different level of accountant and a different bill. And check whether the zone insists on its own template — IFZA only accepts the simplified form on its own template, and the wrong format means redoing the work at renewal season.
How we match the free zone to your reporting
We do not start from the licence package — we start from three numbers: expected turnover, headcount and any plans for QFZP status. From those we work out whether the federal requirement applies, whether the simplified form will be enough, and where annual reporting costs stay predictable. We then check that against the free zone’s current regulations, not its marketing page, and where no public document exists, we send a written query to the administration before registering.
Tell us what the company will do and what turnover you expect in the first year, and we will match you to a free zone where reporting never becomes a surprise, along with a realistic cost of ownership.
Get a consultation
This material is for information purposes and reflects the state of regulation as of September 2026. Free zone regulations and Ministry of Finance decisions change; before making a decision, verify against the current version of the relevant documents and with the administration of the specific free zone.