Mauritius is not an offshore haven in the old sense of the word. It is a well-regulated jurisdiction with a solid reputation, a broad network of tax treaties and a transparent corporate framework. Below we break down who should open a company in Mauritius, which business forms are available, which taxes apply in 2026, what the costs are built from, and how the process runs — right through to opening a bank account.
Why international businesses choose Mauritius
Choosing a jurisdiction is always a balancing act between tax, reputation and ease of doing business. On all three counts, Mauritius holds a strong position. Its legal system is built on English common law, which makes cross-border deals smoother and keeps the framework familiar to lawyers around the world. Corporate tax sits at a headline 15%, yet on certain categories of foreign-source income the effective rate drops to roughly 3%. There is no capital gains tax and no dividend tax, and there are no exchange controls.
Reputation deserves a separate mention. Mauritius is not a “grey” offshore centre: the country was removed from the FATF grey list in 2021 and from the EU AML list in 2022. For banks and counterparties this is decisive — a Mauritius company is treated as a structure from a regulated jurisdiction rather than an anonymous scheme.
Finally, the network of double taxation agreements (DTAs) covers dozens of countries and is particularly valuable for business with Africa and India. This is precisely why Mauritius has historically been used as a “bridge” into those regions. Compared with the UAE, where substance requirements keep tightening, Mauritius company formation often turns out to be the more flexible route for holdings and investment structures.
Who it suits
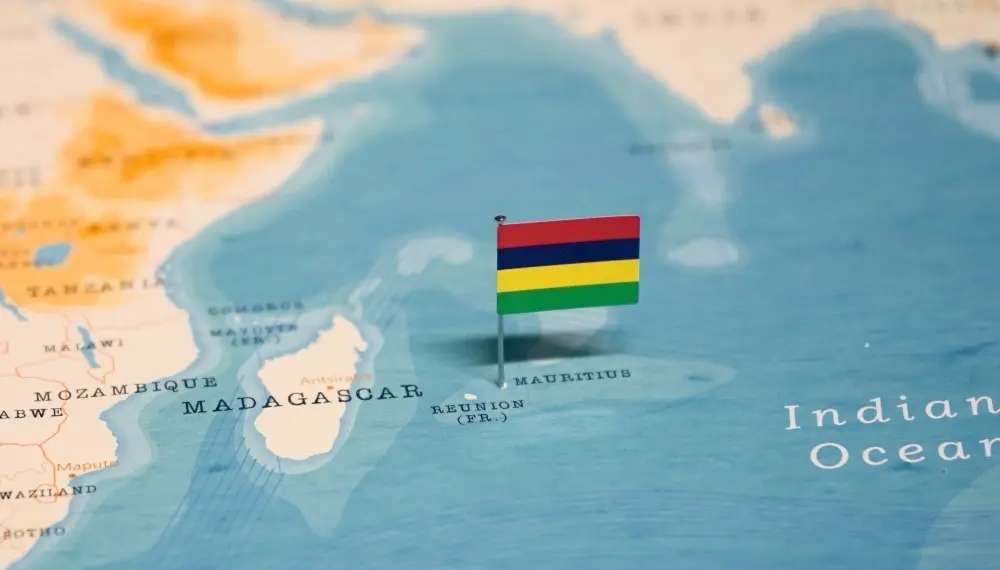
Let us be honest: the jurisdiction is not for everyone. If you are planning a purely local business with a physical footprint in another country, there are simpler options. But when the goal is an international structure, Mauritius truly comes into its own. To set up a company in Mauritius makes sense in several scenarios:
- International trade — a company acting as the hub for contracts, settlements and profit distribution.
- Investment structures — funds, holdings and asset management.
- IT and digital — SaaS, marketing and service companies with no ties to a single geography.
- Consulting and services — serving international clients through a regulated jurisdiction.
- Entry into Africa and India — using Mauritius as a transit hub under its DTA network.
If the entire objective is simply to “pay less tax”, other solutions are worth a look. But if you want to structure an international business properly, Mauritius is a well-founded choice.
Types of companies you can set up
The jurisdiction offers several forms, and the right one depends on your goals. The core vehicle for international business is the Global Business Company (GBC) holding a Global Business Licence (GBL) from the Financial Services Commission (FSC). This company is treated as a tax resident of Mauritius and gains access to the DTA network. The former GBC2 category was abolished in 2019, and its role passed to the format described next.
The Authorised Company Mauritius is the closest thing to a classic offshore company: its business and management are conducted mainly outside Mauritius, so it is treated as a non-resident and is not taxed locally, though it must still file a return with the Mauritius Revenue Authority (MRA). The Domestic Company is intended for operating on the local Mauritian market. In addition, trusts are available for asset protection and funds for investment purposes.
| Parameter | GBC / GBL | Authorised Company | Domestic Company |
|---|---|---|---|
| Best suited to | International business, holdings | Offshore activity outside Mauritius | Local market |
| Tax status | Resident, 15% (eff. down to ~3%) | Non-resident, not taxed in Mauritius | Resident, 15% |
| Access to DTAs | Yes | No | Yes |
| Licence / registration | FSC (GBL) | FSC (authorisation) | Registrar of Companies |
In short: when a client says they want to open an offshore company in Mauritius, they usually mean a GBC with a GBL licence — because it delivers both reputation and access to tax treaties.
Main requirements
The requirements here are real, and that is part of what protects the jurisdiction’s reputation. A company holding a GBL licence must establish genuine economic substance in Mauritius — otherwise it cannot obtain tax-resident status or access to the DTA network. In practice this means several mandatory conditions:
- At least two resident directors — a firm requirement for a GBL and for demonstrating substance.
- A registered office — arranged through a licensed management provider.
- A company secretary — mandatory for the company.
- Genuine activity — management and key decisions are taken in Mauritius.
- KYC and due diligence — rigorous checks on beneficial owners and source of funds.
Banks look at the origin of funds, the business model, real activity and the international structure of the company. Opening an account therefore calls for preparation, not just a formal submission of documents. More on that below.
Taxes in Mauritius in 2026
The tax system is one of the reasons the jurisdiction is so popular. For international business it remains comfortable, but since 2024–2025 a few nuances have appeared that are worth keeping in mind.
- Corporate tax — 15%. Thanks to an 80% partial exemption on specified categories of foreign-source income — foreign dividends, interest, income from the leasing of ships and aircraft, and others — the effective rate on that income drops to roughly 3%, provided substance requirements are met.
- Dividend tax — 0%. There is no withholding tax on dividends.
- Capital gains — 0%. There is no separate capital gains tax (CGT) in Mauritius.
- VAT — 15%. Applies where there is taxable turnover in Mauritius.
There are no exchange controls, capital moves freely and reporting is transparent. That said, new levies have been introduced. From the year of assessment starting 1 July 2025, a QDMTT — a domestic minimum top-up tax of 15% applies to multinational enterprise (MNE) groups with consolidated revenue of €750 million or more; ordinary SMEs are not affected. Companies with turnover above MUR 50 million are subject to the CCR (Corporate Climate Responsibility) Levy of 2% on chargeable income (from 1 July 2024). And the Fair Share Contribution introduced in 2025 does not apply to GBL holders — a clear plus for international structures.
| Tax | Rate | Comment |
|---|---|---|
| Corporate tax | 15% (eff. down to ~3%) | 80% exemption on specified foreign income |
| Dividends | 0% | No withholding tax |
| Capital gains | 0% | No CGT in Mauritius |
| VAT | 15% | Where there is taxable turnover in Mauritius |
| QDMTT (large MNEs) | 15% | Groups with revenue ≥ €750M, from 01.07.2025 |
The final burden depends on the company form, the type of income and whether substance requirements are met, so the specific structure is best modelled during a consultation.
How much it costs
This is not a jurisdiction where you can quote a single figure and end the conversation. The cost is made up of several parts: government fees, the services of a licensed provider (directors, secretary, office), banking support and accounting. If these are not factored in from the start, unpleasant surprises tend to surface later, which is why we discuss the cost structure with the client up front.
| Cost item | Indicative (USD) | Depends on |
|---|---|---|
| GBL registration & setup | from 4,500 | Structure, number of participants |
| Resident directors & secretary | from 2,000 / year | Substance requirement |
| Registered office | from 800 / year | Through a licensed provider |
| Bank account opening | from 1,000 | Bank and client profile |
| Accounting & reporting | from 1,200 / year | Volume of transactions, audit |
| Annual renewal | from 3,500 / year | Company type |
One important point: every project is individual, and the final cost is always shaped around the specific case — the chosen company form, the type of activity, the ownership structure, the bank’s requirements and the scope of support. Service fees therefore vary from project to project, and there is no universal price list. We calculate a precise quote after a short consultation, once the goals of the business and the registration scenario are clear. That way you pay for the work you actually need rather than for an averaged package. And it is always worth counting not just the setup but the annual maintenance too — that is what makes the picture realistic.
Registration timeline
The process here is more structured than in some “fast” jurisdictions, but it is predictable in return. When the documents are prepared correctly, everything moves without delays:
- Structuring — 2–5 days: we discuss the objectives, select the company form and agree the details.
- Company registration — 5–10 business days: filing the documents and receiving the registration data.
- Bank account opening — 2–6 weeks: bank review, compliance checks and final approval.
A full cycle usually takes around a month, sometimes a little more. The banking stage is by far the longest — that is normal practice, not a problem specific to any one case. We prepare the documents in advance and stay with the client through to the result, so the review runs smoothly.
How to open a company: step by step
At first glance, opening a company looks like nothing more than filing documents and receiving a certificate. In practice, the nuances matter at every stage, and it is at the joints between the steps that delays most often arise. We guide the client through in order:
- Analysing the objective and structure — we define why the company is needed: trade, investment, IT or a holding. That shapes the entire model.
- Preparing the documents — details on beneficial owners, source of funds and a description of the business.
- Registering the company — we file the documents, obtain the certificate and put the legal foundation in place.
- Appointing resident directors — a mandatory requirement for compliance with the rules.
- Opening a bank account — the key stage, without which the company remains only “on paper”.
- Setting up operations — accounting, contracts and day-to-day activity.
The process is not complicated in itself, but every stage involves checks. The point of proper support is to close the gaps between the steps so there are no pauses and no returned applications.
Opening a bank account: where difficulties arise
Company registration usually raises fewer questions. The bank, on the other hand, is where it gets interesting. Banks in Mauritius work to international standards and assess not only the company but also the beneficial owner and the business model as a whole. Many arrive expecting a formality, yet it is this very stage that decides whether the company will really function. The bank examines the structure of the business (who the owner is and whether the model makes sense), the source of funds and its documentary evidence, the description of real activity, the geography of operations and the beneficial owner’s track record. The point here is not to “guess the answers” but to build a clear story in advance. When the structure is put together logically, the review goes calmly; when it is merely formal, the bank senses it. We prepare the client ahead of time — what they will be asked, which documents are needed, how to frame the business model. That saves weeks, because the typical unprepared scenario is a cycle of returns and repeat checks.
Documents needed
It is not only the presence of documents that matters, but their quality: regulators and banks look at the detail. The standard package includes:
- passport and proof of address — basic identification;
- beneficial owner’s CV — shows experience and a connection to the business;
- description of activity — what the company will actually do;
- proof of source of funds — one of the key items;
- bank statements — sometimes requested in addition.
Once the package is assembled, the review begins, and here the bank looks at the overall picture: how coherent everything is and whether there are any contradictions. We check the file before submission — a simple step that noticeably improves the odds of the account being opened.
How Dynasty Business Adviser delivers results
In theory, you can do all of this yourself. In practice, most clients come back after the first difficulties — usually at the banking stage. Our job is not simply to register a company but to hand over a working business tool. So we take on the whole process: we unpack the objective and select the right company form, register it without unnecessary iterations, prepare the file for the bank (the stage where we add the most value), stay with the client through to the account being opened rather than just filing documents, and help with the launch — accounting, contracts and operations. As a result, the client is not left alone at any stage. This matters all the more if you have no experience with international structures: we close the questions that usually only surface midway through.
Ready to open a company in Mauritius?
Mauritius suits those building a durable international structure: a regulated jurisdiction, an effective rate from ~3% on qualifying income, no tax on capital gains or dividends, access to the DTA network and to the markets of Africa. To make the journey without bank refusals and needless iterations, entrust the structure and support to professionals. Get in touch with Dynasty Business Adviser — we will select the company form, prepare the documents and take the process through to a working account.
Get a consultation: ☎️ +971 52 634 1022 · info@dynasty-uae.com
Disclaimer: this material is for information purposes only and does not constitute legal or tax advice. Tax rates, fees and regulatory requirements are subject to change. Confirm the current conditions for your specific activity during an individual consultation.