A client came in with a request that sounds simple: “I don’t want my family fighting over the business in court after I’m gone.” The estate held shares in two operating companies, three residential properties, and a brokerage account — all registered to one individual. The problem isn’t the assets themselves. It’s that everything sits in a personal name, so the day that person dies, several countries’ inheritance rules switch on at once, whether the family wants them to or not.
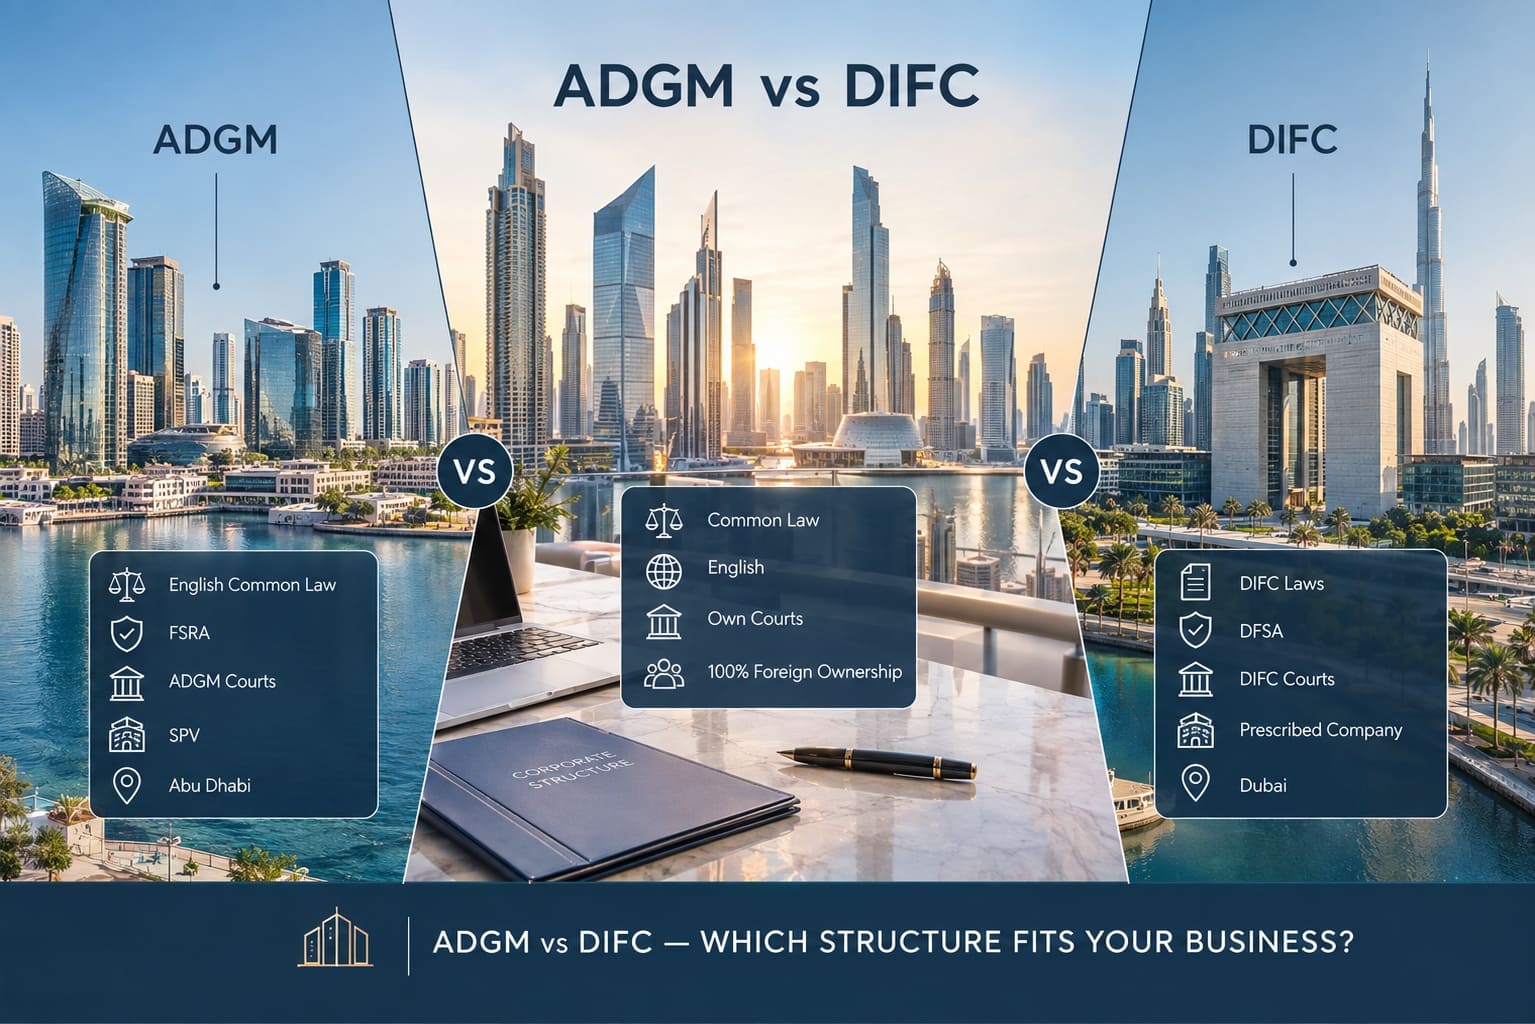
An ADGM foundation solves this with mechanics, not promises. Abu Dhabi Global Market (ADGM) is Abu Dhabi’s financial free zone, and an Abu Dhabi foundation registered there sits under its own dedicated legal regime. To set up a foundation in ADGM is to move assets into a distinct legal entity with no shareholders, and to write the rules for managing them yourself, in advance. Below is what the regulations require, who runs the foundation, what protection the law genuinely gives — and where it stops — what outsiders can see, and how the foundation is taxed.
Why a Foundation, Not Another Holding Company
A company has shareholders; shares have heirs; heirs have their own ideas about what to do with a business. A foundation works differently. From the date of registration it’s an independent legal person — it can sue and be sued — but no one holds an interest in it.
The core point is written into the regulations directly: assets transferred to the foundation become its assets, with full legal and beneficial title. They stop being the founder’s property, and don’t become a beneficiary’s property until the foundation distributes them under its charter. The founder’s death doesn’t trigger a division of assets — the foundation carries on operating under the document the founder wrote while alive. That’s what makes a private foundation in the UAE a different tool, not a rebranded holding structure.
Table 1 — ADGM Foundation vs. a Holding Company
| Factor | Foundation | Holding Company |
|---|---|---|
| Who owns it | No one — a foundation has no shareholders | Shareholders |
| What happens on death | Nothing — the foundation continues | The shares enter the estate |
| Distribution rules | Charter and by-laws, written in advance | Shareholder resolutions |
| Minimum assets | USD 100 | Share capital, at the founder’s discretion |
| Who runs it | A council of at least two people | Directors, appointed by shareholders |
The difference is practical, not theoretical. It’s exactly why a foundation gets chosen when the task is “pass this on,” not “hold this.”
What the ADGM Registrar Requires at Registration
Registration runs under the Foundations Regulations 2017, a framework that has been amended repeatedly since it came into force, most recently by an amendment published on 24 April 2026. The filing package itself is fixed in the regulations, and there’s nothing extra to it.
The Registrar needs a written charter signed by the founder or founders, the registration fee, a declaration of compliance from the applicant, a licence application under the Commercial Licensing Regulations 2025, and a set of confidential particulars. A separate application on the foundation’s initial beneficial owners is filed under the Beneficial Ownership and Control Regulations 2022.
If the charter doesn’t meet the regulations’ requirements, the Registrar must tell the applicant why, in writing, within one month of the filing. The certificate of incorporation is issued electronically; a paper copy bearing the Registrar’s signature or seal can be requested separately.
Table 2 — Mandatory Foundation Parameters at Registration
| Requirement | Detail |
|---|---|
| Name | Must end with the word “Foundation” |
| Initial assets | At least USD 100, or the equivalent |
| Registered address | In ADGM; may match the Company Service Provider’s address |
| Council | At least two councillors |
| Guardian | Required once there is no living founder |
| Service provider | A Company Service Provider is required unless the foundation is exempt |
| Documents | Charter plus by-laws |
Every line gets checked before filing goes in. A rejection doesn’t cost money — it costs time, and it’s almost always the charter that causes it.
The Charter and By-Laws: Two Documents, Two Jobs
The charter is the foundation’s public-facing document. The regulations set out what must appear in it: the name, the founder’s name and address, the foundation’s objects, a description of the initial assets, provisions for establishing the council, the registered office address, and the duration or the event that ends the foundation. One line is reserved for the Designee — the person named to become beneficiary in a single case: if the foundation has no other beneficiary left.
The by-laws are the internal document, and everything that shouldn’t sit in a public charter goes there instead. The council’s functions and the procedure for appointing and removing councillors and the guardian must appear in either the charter or the by-laws; in practice, they go into the by-laws. That’s also where you set out when assets get distributed, accumulated, or used, how beneficiaries are added and removed, and what conditions a recipient has to meet before receiving anything.
Where the two documents conflict, the charter wins. So the line between them needs to be drawn at the drafting stage — not fixed after registration.
Who Decides: The Council, the Guardian, and the Founder
The council is at least two councillors, and a councillor can be the founder personally or a legal entity. The regulations spell out councillor duties in detail: act under the charter, use powers only for their intended purpose, act honestly and in the foundation’s interests, exercise independent judgment, take reasonable care, avoid conflicts of interest, and disclose one before any transaction it touches.
The guardian is the oversight role. While the founder is alive, the regulations leave the guardian question to the charter. Once there’s no living founder, a guardian becomes mandatory. A guardian can be a beneficiary and can be a legal entity, but cannot be the founder, a council member, or the sole beneficiary.
There’s a separate block covering reserved powers.
The charter or by-laws can reserve to the founder, or to someone else, the right to amend, revoke, or vary the charter and by-laws, to change the foundation’s objects and wind it up, to direct or approve investment activity, to appoint and remove councillors and the guardian, to add and remove beneficiaries and change their rights, and to carry out the migration of a foreign foundation into ADGM. One restriction holds regardless: any disposal of the foundation’s assets has to go through a council resolution.
Tell us what you hold and who should receive it — in a single meeting, we’ll tell you whether the task fits an ADGM foundation.
Asset Protection: What the Regulations Give and Where It Stops
This is where asset protection UAE structures either deliver or don’t, so the limits matter as much as the promises. The regulations contain three rules that do real work.
- First: a transfer of property to the foundation cannot be held void, voidable, or set aside by reference to a foreign forced-heirship rule, or to any other foreign law. A foreign judgment isn’t recognised or enforced to the extent it conflicts with this rule.
- Second: the foundation itself, and the transfer of property to it, aren’t unwound because of the founder’s bankruptcy, the liquidation of his estate, or creditors’ claims — regardless of what any foreign law says.
- Third: a beneficiary has no proprietary interest in any specific foundation asset, and assets available for distribution to a beneficiary can’t be seized in that beneficiary’s bankruptcy or attached by that beneficiary’s creditors.
Now the limit, better stated upfront than discovered later. If a court finds that the founder was insolvent at the time of the transfer, or intended to defraud a creditor, the court can void the transfer to the extent of that creditor’s claim. The burden of proof sits with the creditor — but the rule exists. The practical takeaway is simple: set the foundation up early, in a calm period, not after a claim has already been filed.
What Outsiders Can See
The Registrar keeps a separate register of foundations, and what goes into it is a closed list: the name and registration number, the name and address of the Company Service Provider, the name and address of each council member, the date of establishment, and a record of annual fee payments.
Beneficiaries, the by-laws, and the composition of assets aren’t on that list. Accounting records, reports, and returns aren’t subject to public disclosure by the Registrar. Beneficial ownership information is filed with the Registrar under a separate regime — it isn’t a public window, but it isn’t invisible either.
That balance is usually what a family needs: a counterparty sees who runs the foundation, not who benefits from it.
Tax Status: The Family Foundation and Transparent Treatment
Under federal corporate tax law, a foundation is by default a taxable person in its own right: zero percent up to the taxable-income threshold, nine percent above it. The law itself doesn’t fix that number — it’s set separately, by Cabinet Decision, currently AED 375,000.
There’s a distinct provision for a UAE family foundation. A Family Foundation may apply to the tax authority to be treated as an Unincorporated Partnership — that is, transparently. This is an application, not an automatic status. The conditions are listed in the law: the foundation is established for identified or identifiable individuals, a Non-Profit Organisation, or both; its main activity is receiving, holding, investing, distributing, or otherwise managing assets and funds connected with savings or investment; it doesn’t carry on activity that would count as a business if done directly by the founder or the beneficiaries; and avoiding corporate tax isn’t the foundation’s main purpose. That list isn’t exhaustive — the law leaves the Minister free to prescribe further conditions.
Once approved, transparent treatment applies from the start of the tax period in which the application was filed, from the following tax period, or from another date the authority sets. The authority can request information and records to check the conditions are still met — the status has to be maintained, not just obtained once.
The UAE Federal Tax Authority publishes a dedicated guide on taxing family foundations; the current edition is dated June 2026. Whether transparent treatment extends to companies held under the foundation is worked out at the level of subsidiary legislation and that guide — we confirm the position for a specific structure rather than apply a general rule to it.
Migrating a Foreign Foundation into ADGM
If a foundation already exists somewhere else, it doesn’t have to be wound up first. The regulations allow continuation instead: a foreign foundation that has legal personality and property can apply to register in ADGM, provided its own constitutional documents and the law of its place of establishment allow it. Once it registers in ADGM, it has to deregister from wherever it was registered before.
Migration isn’t available if the foundation is bankrupt, in liquidation, has a liquidator, receiver, or administrator appointed, or has a court application pending to open insolvency proceedings. The package includes the existing charter and an amended version meeting ADGM’s requirements, particulars of the council members and the guardian, confirmation that the migration is permitted under the law of the place of establishment, a solvency statement, and evidence of legal personality.
The route out is covered too: before filing to exit, a foundation must give creditors 31 days’ written notice and publish that notice once; creditors then have 30 days to object.
What a Foundation Cannot Do
A foundation’s objects have to include managing its assets and income and distributing them through council resolutions under the charter. Unlawful activity, and activity contrary to the public policy of ADGM or the UAE, is excluded outright.
Since April 2026, there’s one more restriction on top of that: a foundation may not carry on activity so as to constitute a Non-Profit Organisation. The Registrar can, on written application, lift that restriction or apply it with conditions, if satisfied that the proposed activity fits the foundation’s objects and doesn’t undermine ADGM’s regulatory framework. A breach is a breach of the regulations, and liability reaches the foundation itself along with any councillor, founder, or guardian found to be in default.
A foundation also has to keep adequate accounting records and retain them for ten years. An audit isn’t continuously required, but the Registrar can demand one in writing.
What Our Work Covers
We start with a map, not a form: which assets transfer in, in what order, who gets paid and under what conditions, who controls the council, and what happens on the death or incapacity of each key person involved.
Next comes the document architecture. The charter and by-laws get drafted against that map: how power is split between the council, the guardian, and the founder, which powers are reserved, how beneficiaries are added and removed, the mechanics of payments, and the scenario for winding the foundation up. Then filing: the Registrar’s package, the beneficial ownership application, the licence, the address, and a Company Service Provider unless the foundation qualifies as exempt.
After registration, the work continues: notifications to the Registrar within the set deadlines, record-keeping, tax registration, and — where the situation calls for it — the application for family foundation status.
How to Start
The first conversation is about assets and people, not paperwork. We look at what’s going into the foundation, who receives what and when, which jurisdictions are involved, and where the structure’s weak point sits — the part of succession planning UAE families tend to skip until it’s too late. You come away with a structure chart and a list of what needs preparing before filing.
Describe your situation, and we’ll come back with a foundation structure and a registration plan built around it.
Get a consultation
*This material is for information purposes only and is not legal or tax advice. ADGM Registrar requirements and tax treatment apply to specific facts and should be verified against your own structure. Information current as of September 2026.*